How to Find the Best Cost Segregation Study for Long Term Rentals

Updated: Sep 11

Most articles about cost segregation for rental property start with the tax savings. This one starts with a harder question...
Can you actually use the deduction this year?
The IRS requires you to depreciate residential rental property over 27.5 years using straight-line depreciation. A cost segregation study does not change that rule. It changes what gets used first.
An engineer walks the property and separates the purchase price into asset classes based on what each component actually is:
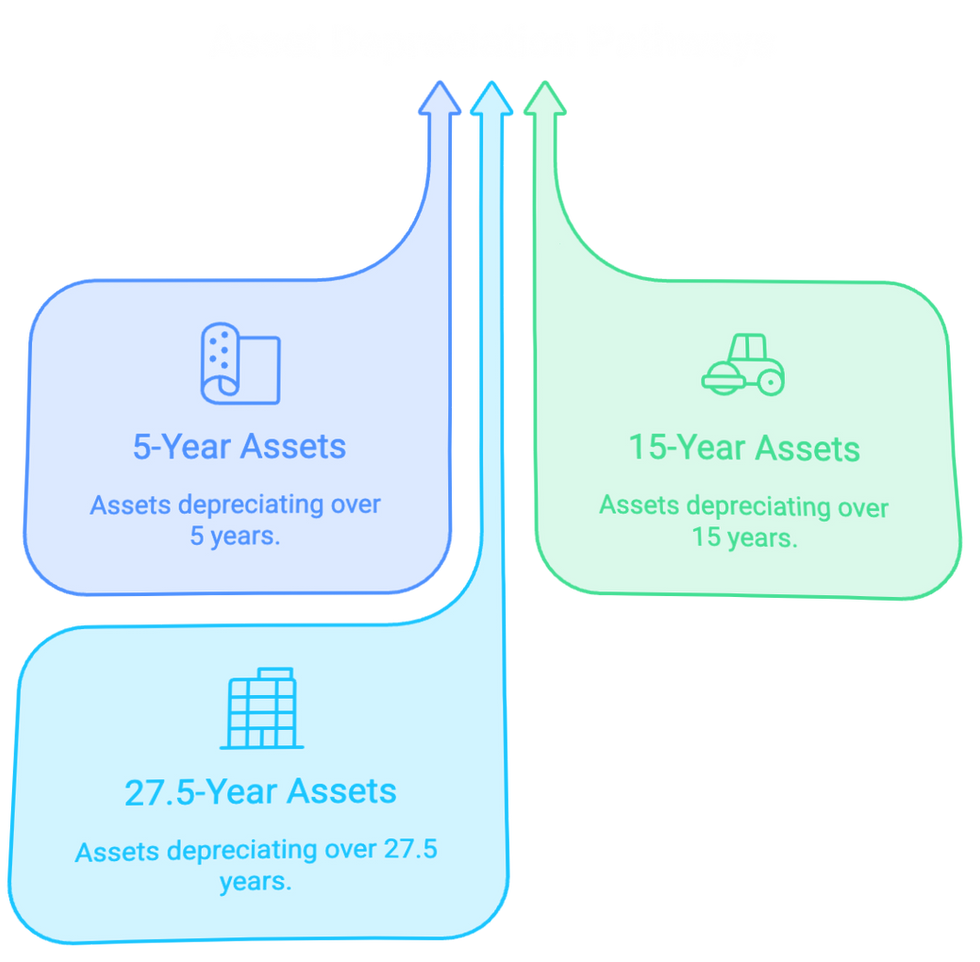
5 years. Removable and non-structural personal property under §1245.
15 years. Land improvements, depreciated over 15 years with a 150% declining balance method.
27.5 years. The building itself and its structural components under §1250.
Land. Never depreciable. It comes out of basis before anything else.
The 5yr and 15yr buckets qualify for bonus depreciation. That is where the first year deduction comes from. The building remains on its original schedule.
A common misconception is that cost segregation creates new deductions. It does not. It moves deductions forward.
You are trading decades of small deductions for one large one, and accepting a lower basis at sale in exchange.
Which Components Actually Reclassify
This is where most online content goes wrong, including content written for investors by firms that should know better. The test is not whether a component is expensive or replaceable. The test is whether it is a structural component of the building under Reg. §1.48-1(e)(2), or whether it serves a function beyond the operation and maintenance of the building.
Reclassifies to 5 years:
Carpet and other removable floor coverings
Appliances, including ranges, refrigerators, and in-unit laundry
Window treatments and blinds
Decorative lighting fixtures
Cabinetry and countertops, depending on how they are affixed
Electrical and plumbing that serves specific equipment rather than the building generally
Removable partitions and millwork
Reclassifies to 15 years:
Parking areas, driveways, and curbing
Sidewalks and hardscaping
Site lighting and site utilities
Fencing and gates
Landscaping and irrigation
Retaining walls
Signage foundations
Stays on 27.5 years:
General building electrical service and distribution
General building plumbing and water supply
HVAC serving the building as a whole
Fire protection and sprinkler systems in residential property
Roof, walls, foundation, windows, and doors
Permanently installed flooring such as glued tile or sheet goods
Central security and alarm wiring integrated into the structure
A lot of RE investors list electrical, plumbing, HVAC, and fire suppression as accelerated assets. In a residential rental, those are structural components that should stay at 27.5. A provider who promises otherwise is either describing a narrow exception without saying so, or setting you up for an audit.
The exception is real but specific. A dedicated electrical circuit serving a single appliance can qualify. Building service electrical does not. The distinction lives in the engineering detail, which is exactly why the study needs an engineer.
What Does Cost Segregation Study for Long-Term Rentals Actually Reclassify
Short-term rentals generally reclassify a higher percentage of basis. They carry furniture, electronics, kitchenware, and decor that a LTR does not, because tenants furnish their own units. More personal property means more acceleration.
Typical outcomes look roughly like this:
Property type | Commonly accelerated 5 or 15 year |
Single-family long-term rental | 15% to 25% |
Small multifamily long-term rental | 20% to 30% |
Furnished short-term rental | 25% to 35% |
These are ranges, not promises. A residental rental on a small lot with no parking, fencing, or landscaping will land at the bottom. A multifamily property with parking, site lighting, and extensive grounds will land higher, because land improvements carry most of the value.
The honest version of the LTR advantage is different. LTRs tend to have larger site improvement components relative to interior finishes, and they hold their asset classifications longer because tenants do not churn as often.
The benefit is stability and defensibility.
Can LTR Investors Actually Use the Deduction?
Rental real estate is passive by default under §469(c)(2). That is not a judgment about how hard you work. It is a statutory rule, and it applies to long-term rentals regardless of hours.
A passive loss cannot offset wages, business income, or portfolio income. It suspends and carries forward until you have passive income to absorb it or you dispose of the activity in a fully taxable transaction.
3 Paths Get Around This...
Real estate professional status. Under §469(c)(7), you must spend more than half of your personal service time in real property trades or businesses, and more than 750 hours in those activities during the year. Both tests apply. For a married couple, one spouse must satisfy both on their own, though material participation can count the other spouse's time. Clearing REPS makes your rentals non-passive only if you also materially participate in them, which usually requires a grouping election under Reg. §1.469-9(g) to treat all interests as a single activity.
The $25,000 special allowance. If you actively participate and your modified AGI is $100,000 or less, you can deduct up to $25,000 of rental losses against other income. The allowance phases out between $100,000 and $150,000 of MAGI and disappears entirely above that. These thresholds are not indexed and have not moved since 1986.
Passive income to absorb it. Other passive activities generating income can soak up the loss.
If none of these apply, the deduction still exists. It just waits. For an investor who plans to hold for years and eventually sell, suspended losses release at disposition, so the study is not wasted. For an investor expecting to cut this year's tax bill, it changes the answer entirely.
Note that the STR loophole does not help here. Properties with an average guest stay of seven days or less fall outside the §469 rental definition, which is why STR owners can sometimes achieve non-passive treatment through material participation alone. A LTR cannot use that path.
Finding & Evaluating a Provider
Start with a directory that lets you filter by property type and credential rather than working through search results one firm at a time. The FindCostSeg directory organizes providers by specialization, service scope, and professional certification.
A directory listing is a starting point for a shortlist, not a substitute for diligence.
Credentials worth confirming:
Licensed engineers with residential property experience
CPAs or EAs who handle real estate taxation regularly
Membership in the American Society of Cost Segregation Professionals, which maintains a certification program and technical standards
Demonstrated experience with properties comparable to yours
The Short Version
When you conduct a cost segregation study on a long-term rental, you can typically shift about 15% to 30% of the property's basis into 5 and 15-year classes. Combine that with 100% bonus depreciation, this can translate into a solid first-year deduction.
However, whether this actually results in the current year tax reduction hinges on §469, and for many long-term rental owners, the straightforward answer is not always a "yes".
Start by addressing the passive loss issue. After that, when evaluating providers, focus on their engineering expertise and the quality of their documentation, rather than just the size of the numbers they project in sales.
Take some time to research cost segregation providers based on property type and their credentials to create a solid shortlist.
This article is general information, not tax advice. Cost segregation outcomes depend on your property's basis, construction, in service date, entity structure, and personal tax situation. Work with your CPA or tax advisor before buying a study or claiming accelerated depreciation.


Comments